
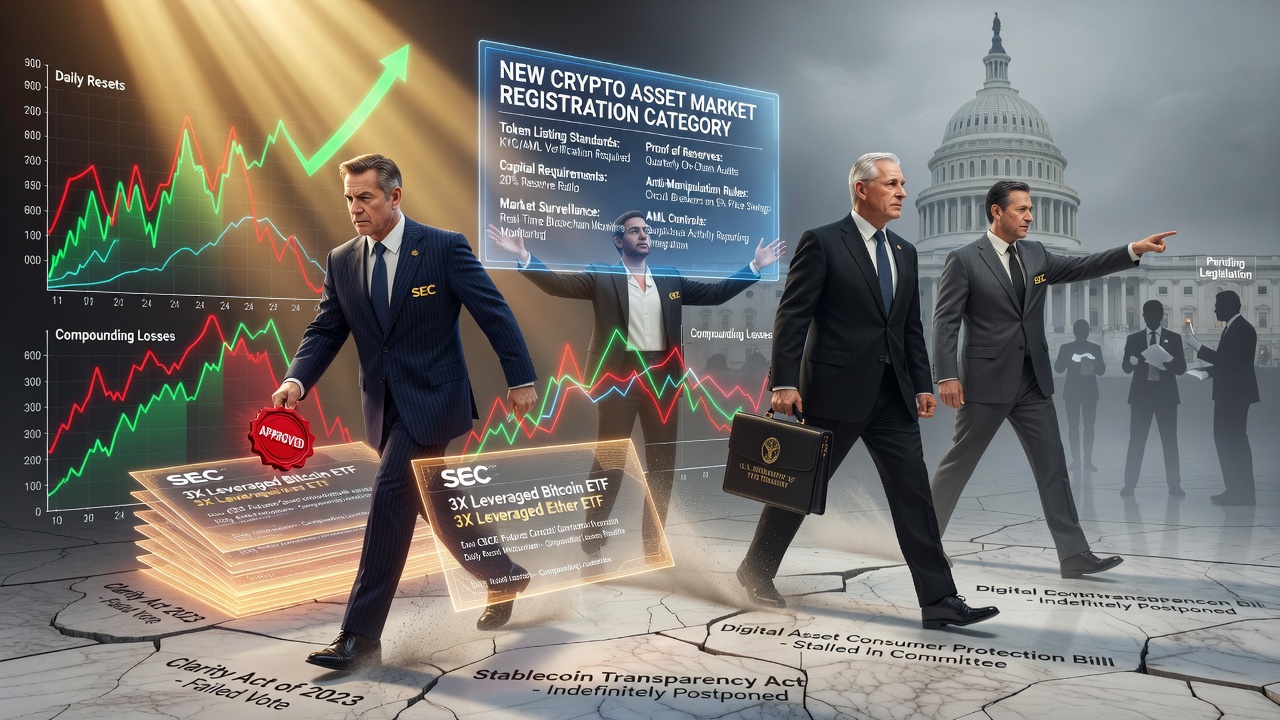
Three separate stories converged this week to show how federal regulators are filling the gap left by a failed legislative effort. Strive, a corporate Bitcoin treasury company, bought 2,000 bitcoin for roughly $169 million, pulling it within striking distance of Marathon as one of the largest public holders of the asset. At the same time, the Securities and Exchange Commission approved the first 3X leveraged bitcoin and ether funds, and the Commodity Futures Trading Commission floated a federal framework for leveraged retail crypto trading. None of this happened because Congress passed the Clarity Act. It happened because the bill failed, and agencies are now moving on their own.
Corporate Bitcoin Treasuries Split Into Winners and Everyone Else
Strive's purchase this week was nearly six times the size of a comparable buy announced by Strategy, the company that popularized using public markets to finance bitcoin accumulation. Strive's model relies on preferred stock issuance rather than the mix of convertible debt and preferreds that Strategy has used over time. That distinction matters to investors: a company can be debt-free and still carry heavy fixed obligations. Preferred shareholders are paid before common shareholders, and dividend commitments tied to that preferred stock function much like a bond coupon, regardless of what label a company puts on its balance sheet. The broader takeaway is that the public bitcoin treasury sector is no longer a single trade. A handful of companies have found financing structures that work in most market conditions, bitcoin miners are pursuing their own pivot toward data centers and AI infrastructure, and a long tail of smaller treasury companies are still searching for a sustainable model. Rising bitcoin prices can flatter all of their stock charts without indicating which of these businesses have durable strategies.
3X Leveraged Funds Are Trading Tools, Not Long-Term Bets
The SEC's approval of 3X leveraged bitcoin and ether products, requested by CBOE and intended to be operated using regulated futures contracts, raises the ceiling from the 2X leverage previously available in US-listed crypto funds. These products are not a way to hold triple exposure to bitcoin's price over months or years. Leveraged ETFs reset their exposure daily, which means returns compound in ways that can diverge sharply from the underlying asset over any period longer than a single trading session.
- A volatile, choppy market erodes returns through repeated daily resets, a phenomenon often called volatility decay.
- Bitcoin can finish a stretch of days roughly flat while a 3X fund tracking it posts a meaningful loss.
- These instruments are built for short-term tactical trading, not buy-and-hold investing, and carry a corresponding risk of misunderstanding by retail buyers.
Regulators approving higher leverage does not change the math of how these products behave. It increases the stakes for anyone who treats them as a simple way to amplify long-term bitcoin exposure rather than a short-duration trading instrument.
CFTC Floats a Federal Category for Leveraged Crypto Exchanges
The CFTC's proposal centers on a new registration category, described as a crypto asset market, that would let exchanges offering leveraged, margined, or financed retail crypto products operate under a federal compliance structure. The agency has acknowledged it cannot force crypto trading onto CFTC-regulated platforms without authorization from Congress, so the proposal works within existing authority rather than waiting for new legislation.
- Token listing standards specific to digital assets, something currently missing from US market structure.
- Market surveillance and anti-manipulation requirements.
- Proof of reserves for pooled customer assets, along with capital requirements and segregation of customer funds.
- Standard risk disclosures, identity verification, and anti-money laundering controls.
- Review criteria for new tokens, including supply concentration, insider holdings, and vesting schedules.
The proposal is now open for public comment, not finalized rulemaking. Its significance lies in the intent: much of today's leveraged crypto trading by US residents happens offshore, through platforms operating outside direct American oversight. A federal framework aims to bring that activity onshore under enforceable rules, giving retail traders clearer protections and giving regulators a defined set of obligations to hold exchanges accountable to.
Parallel Moves at Treasury and the OCC Add to the Pattern
Treasury's decision to withdraw a proposed crypto mixer reporting rule, along with an earlier self-hosted wallet proposal, reflects concern that overly broad reporting requirements would have been unworkable and could have swept in legitimate privacy-preserving transactions alongside illicit ones. Separately, new trust bank applications filed with the OCC show continued friction between fintech firms seeking federal charters and community banks that argue such charters let crypto companies operate bank-like services without equivalent regulatory burdens. Together, these developments describe a regulatory environment adjusting through agency action rather than comprehensive legislation, leaving market participants to track a shifting and still incomplete rulebook.